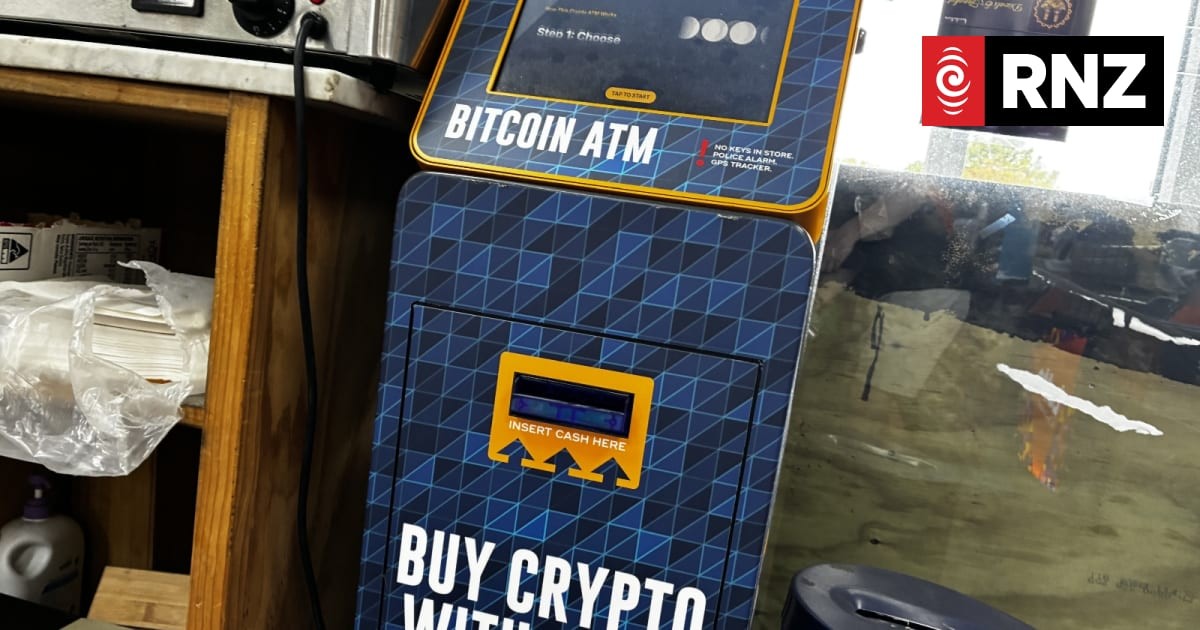
From dairies in Auckland to petrol stations in Invercargill, New Zealand now hosts around 200 cryptocurrency ATMs. These machines let anyone with cash buy Bitcoin or other digital assets in minutes. But as their numbers have grown, so have concerns about scams and criminal misuse. The government has chosen targeted regulation over an outright ban. The question is whether we can get the balance right.
How do crypto ATMs work and why are they spreading?
Crypto ATMs look like ordinary cash machines but serve a different purpose. You feed in cash, scan a QR code, and receive cryptocurrency in a digital wallet. Most machines in New Zealand are one-way: they only let you buy crypto, not sell it for cash. Operators require identity verification before any transaction, which can be completed in just a few minutes.
The first machines appeared over a decade ago, but they remained a curiosity until 2023. That year, commercial operators began rolling out permanent networks. Today, roughly 200 machines are scattered across the country, tucked into everyday spots like vape shops and convenience stores.
What benefits do crypto ATMs offer?
For some New Zealanders, these machines open doors to digital finance. An estimated 51,000 adults were without a bank account in 2021, with barriers hitting victims of family violence, homeless people, former prisoners, people with disabilities, and older New Zealanders hardest. Crypto ATMs offer an alternative path into digital payments.
They also provide access to emerging tools like stablecoins. The Financial Markets Authority recently recognised NZDD, a New Zealand dollar-backed stablecoin, as a legitimate payment tool. For people who rely on cash, crypto ATMs can be a bridge to a digital economy that might otherwise exclude them.
What are the real risks?
The drawbacks are significant. Transaction fees range from 6 to 19 percent, plus flat fees of NZ$1 to $5, exchange-rate markups of 5 to 10 percent, and network fees. That is far more expensive than online exchanges, which typically charge under 2 percent.
More troubling is the fraud risk. Scammers pose as police, the Inland Revenue Department, banks, or tech support, convincing victims to deposit cash into a machine. Unlike credit card payments, crypto ATM transactions are nearly impossible to reverse once completed.
International evidence paints a stark picture. In 2025, the US FBI received over 13,400 complaints involving crypto kiosks, with reported losses exceeding US$388 million. Australia has seen its machine count explode from 23 in 2019 to more than 2,000 today, with its financial intelligence agency linking heavy users to scam proceeds and money-mule activity.
In New Zealand, the Banking Ombudsman has confirmed tens of thousands of dollars lost through crypto ATM scams. The Police Financial Intelligence Unit has identified the machines as an emerging regulatory challenge requiring urgent attention.
How should New Zealand regulate crypto ATMs?
The government is setting new powers to regulate cash transactions involving virtual assets. Options include transaction limits, cooling-off periods, and even a future ban on cash purchases of high-risk assets if harm continues. Officials have been asked to consult with the industry on safeguards.
One obvious step is tiered transaction limits. Australia caps cash deposits at AU$5,000. Some New Zealand operators currently allow up to NZ$9,500. Small purchases could remain largely unconstrained, with larger transactions triggering additional checks.
Nebraska offers a useful model: new customers start with low daily limits and earn higher limits only after establishing a history of legitimate use. Since scam victims are often first-time users, this protects vulnerable people without restricting regular ones.
New Zealand could also introduce a mandatory 24 to 72-hour cooling-off period before an initial transaction, or a confirmation call from the operator. Every transaction should include clear scam warnings in plain English and other languages. Operators should be required to refund properly reported fraudulent transactions and report suspicious activity to police in real time.
These measures should be introduced as a package, with stronger restrictions kept in reserve if problems persist.
What can you do to stay safe?
Until stronger safeguards are in place, there is one simple rule: treat any request to deposit cash into a crypto ATM on behalf of someone else as a potential scam. If it feels wrong, it probably is.
Olena Onishchenko is a senior lecturer in finance, and Murat Ungor is a senior lecturer in economics, at the University of Otago.